Showing posts with label Kiplinger. Show all posts

Thursday, February 14, 2013

Kiplinger: The Cost of Alzheimer's


Credit for this belongs to Kipliger.  You can view the 8 minute video @: Kipliner.com       Search: Alzheimer's

50% of those who are age 80 will have Alzheimer's


Even if you don't by Long Term Care Insurance see an Elder Law Attorney for:

The cost of care is anticipated to increase by 5% a year


MAY cover the costs of ... drugs?
 Long Term Care Insurance must be purchase before you lose your health.

Pertains primarily to Early Onset of Alheimer's
 Long Term Care Insurance must be purchased before you lose your health. 


Monday, November 26, 2012

LTCi 401: Policy Benefit Choices and Options


This is an attempt to provide a brief outline of the features and benefits of a Tax Qualified Long Term Care Insurance policy. Descriptions of Choices Options and Features will be discussed at another time.

Choices:
When you decide to purchase LTCi your first choice is what type of policy: Reimbursement, Indemnity or Cash benefit?  Secondly the daily amount: $50-$400 a day.  Then in order to determine the TOTAL amount available in your policy you have a choice of 365 days 1Year (CA Partnership Only) 730 days 2 Year, 1,095 days 3 Year, 1460 Days 4 Year etc.  Some companies may still offer Unlimited (Life Time).

Example: (Reimbursement-No inflation protection)
          $200 of Daily benefit x 1,095 day = $219,000 of Total benefit.
A.   Maximum amount available is no more $200
B.   Total Benefit to be received is $219,000 (LTCi Account Value)
C.   One purchases is dollars not time.  IF one chooses to be reimbursed $100 a day for services received the benefit will last twice as long (6 Years)
Other benefits possibly included in a basic policy: Equipment and Home Modification, Caregiver Training, Respite Care, Bed Reservation, Care Management, Medical Alert, Ambulance service

Options
When considering the purchase of Long-Term Care Insurance there are many options that one needs to consider.  Options increase the cost of the policy.  Some options, like Automatic Inflation are recommended in order to keep pace with the cost of care.  Other options such as Restoration of Benefits are unlikely to occur and are priced accordingly.
Here is a list of options (not all) that are found in policies.  Remember that definitions of these options defer between companies.
·         50%-100% of Nursing Home Benefit for Home Care
·         70%-100% of Nursing Home Benefit For Residential Care
·         Daily or Monthly reimbursement for Home Care
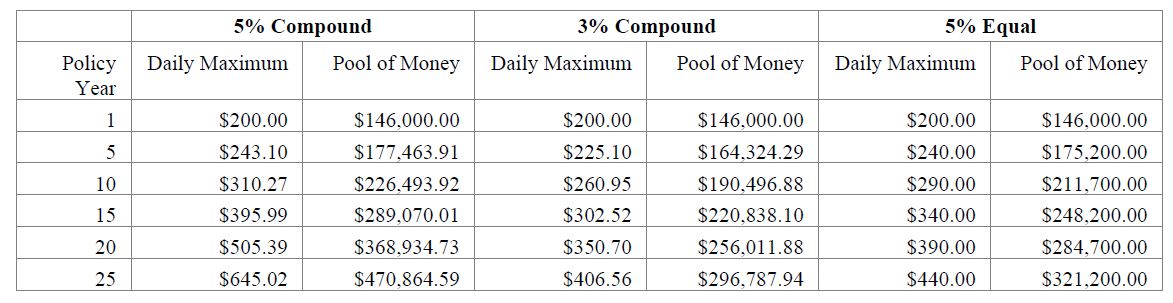
  •           Automatic Inflation Protection
o   5% Compound
o   3% Compound
o   5% Simple

(Provided by Genworth)
o   CPI (Consumer Price Index) Inflation protection
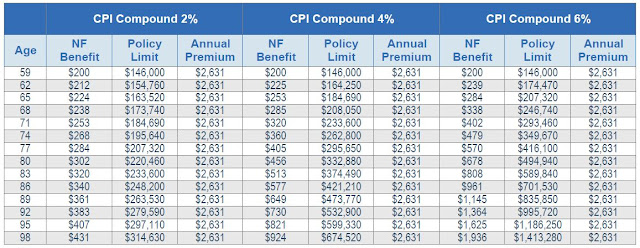

(Provided by John Hancock Ins.)


·         Elimination Period 30, 60, 90, 180, 360 Days
o   Calendar Days or Service Days
o   Without or With: Waiver for Home Care Service
·         Shared-care Benefit
·         Survivorship and Waiver of Premium
·         Dual Waiver of Premium
·         Restoration of Benefits
         Nonforfeiture 


Wednesday, October 10, 2012

LTCi 202: Filial Responsibility


In California as well in about 30 other states there currently are laws making adult children responsible for their parents if their parents can't afford to take care of themselves.  California's Family Code (Sec. 4400) states "Except as otherwise provided by law and adult child shall to the extent of his or her ability, support a parent who is in need and unable to maintain himself or herself by work."

Although California is not currently enforcing this code.   With the passage of the Deficit Reduction Act. and California's eventual implementation it, (SB 483) children could soon be found responsible for the parents well being legally as well as morally.  Read More

This concern should be discussed further with an  Estate Planning  or Elder law attorney.  Two solutions are:

Life Insurance: You may purchase life insurance for your parents.  You would be the owner of the
of the policy and after your parent's death, the proceeds could be used to pay final long-term care bills.

Long-Term Care Insurance: If your parents who qualify, but can not afford , long-term care insurance, you may buy the coverage for them, it could help reduce or eliminate the cost of their care.

Tuesday, September 4, 2012

LTC 101: The Kiplinger Financial"Who Cares?" video


The Knight-Kiplinger Financial video "Who Cares? Kiplinger's No-Nonsense Look at Long-Term Care and How To Pay For It" link: 

 http://www.kiplinger.com/video/v.php/who-cares-37227843001.html  

This video first was introduced to LTCi Agents in 2008.  Although, brought to you by John Hancock, it is a fine presentation that has held up well over the years. 

Only 22 minutes long great start on understanding Long-Term Care and LTC insurance.


              Steven Hawking reacts to long-term care insurance.


Monday, September 3, 2012

LTC 101: Policy Design (short-fat vs long-thin)

Two ideas prevail when developing a LTC Reinbursment policy.
1: Short - Fat: A short elimination period (30 or 90 days) of $200 to $400 a day benefit with a two, three or four year multiplier.  
Example $200 x 1095 day = $219,000 first year policy value, 90 day facility 0 day home care, 5% compound inflation. 
    Annual Premium 50 year old couple  $2,708 
 (United of Omaha- Std)
Advantage: Client controls the cash flow.  Depending upon need (cost and length of care) sends all or part of  the covered benefits. 
2. Long-Thin: less Daily benefit x 5 year to eight year multiplier with a long elimination period (180 or 365).
Example: $100 x 2,920 = $292,000 first year value. 365 day elimination period , 5% compound.
    Annual Premium for 50 year old couple $2,356 
 (United of Omaha- Std)
Advantage: Premiums savings because client self insures for the short term.  Only for the catastrophic -LONG TERM- does he have access to the insurance benefit.


Note: Short-Fat design with access to more money earlier is best:  The savings gained for a LONG waiting period does not offset the exposure to the early cost of care. 

Long-Term Care Insurance can be complicated with many decisions required in designing a comprehensive policy.     

Insureds need to take the time to understand the features and definitions that distinguish  each companies coverage.

 "Long-term care insurance can allow loved ones to care ABOUT YOU …instead of having to care FOR YOU."